Federal Reserve Hints at Two Interest Rate Hikes: What You Need to Know
Anúncios
The financial ground beneath us is shifting. Recent signals from the central bank indicate that consumers and investors alike should prepare for upcoming Federal Reserve Rate Hikes, a strategic move aimed squarely at cooling down persistent inflation across the country.
If you are currently managing a mortgage, juggling credit card debt, or watching your investment portfolio, these monetary policy adjustments will directly impact your wallet. A tighter credit environment means the cost of borrowing is about to get significantly more expensive.
This breakdown cuts through the complex economic jargon to deliver exactly what these impending monetary tightening cycles mean for your financial future. Here is what you need to look out for as the nation’s banking authorities adjust the economic levers.
Understanding the Federal Reserve’s Stance on Interest Rates
The Federal Reserve, often referred to as the Fed, functions as the central bank of the United States, tasked with maintaining price stability and maximizing employment.
Its primary tool for achieving these goals is monetary policy, with interest rate adjustments being a cornerstone of its strategy. The recent signals regarding Federal Reserve Rate Hikes underscore a critical shift in its approach.
Anúncios
These potential hikes are not arbitrary but are a direct response to prevailing economic conditions, particularly the elevated inflation rates observed across the nation.
The Fed aims to cool down an overheating economy by making borrowing more expensive, thereby reducing demand and, consequently, prices. This delicate balancing act seeks to rein in inflation without triggering an economic downturn.
The market has been closely scrutinizing every pronouncement from Fed officials, with the latest hints confirming a more aggressive posture than previously anticipated.
This proactive stance reflects a growing concern within the central bank about the long-term effects of sustained high inflation. The forthcoming Federal Reserve Rate Hikes are a clear signal of the Fed’s commitment to its dual mandate.
The Driving Force: Persistent Inflationary Pressures
Inflation has been a dominant economic theme over the past year, impacting everything from groceries to gasoline and housing.
The Consumer Price Index (CPI) has consistently reported figures well above the Federal Reserve’s target of 2%, prompting urgent action. Several factors contribute to this persistent inflation, including supply chain disruptions, robust consumer demand, and geopolitical events.
The Fed’s assessment suggests that these inflationary pressures are not merely transitory, as initially hoped, but have become more entrenched in the economic fabric.
Anúncios
This realization has solidified the case for monetary tightening, making the prospect of Federal Reserve Rate Hikes increasingly likely. The central bank believes that by raising interest rates, it can effectively address the demand-side components of inflation.
Economists and policymakers are debating the exact trajectory and magnitude required to bring inflation back to target levels. However, there is a broad consensus that some form of intervention is necessary.
The anticipated Federal Reserve Rate Hikes represent a decisive step in this ongoing battle against rising prices, aiming to restore purchasing power for American consumers.
Projected Timeline and Potential Magnitude of Hikes
While the Federal Reserve has not provided exact dates, the phrase “two interest rate hikes in the next 6 months” offers a clear window into their intentions.
This suggests that we could see one hike within the next three months and another shortly thereafter, potentially at consecutive policy meetings. Market participants are already adjusting their expectations based on this guidance, with futures markets pricing in these anticipated moves.
The magnitude of each hike is also a key consideration. Typically, the Fed moves in increments of 25 basis points (0.25%), though larger 50 basis point hikes are not unprecedented during periods of significant economic concern.
Given the current inflationary environment, some analysts are not ruling out the possibility of a more aggressive approach if inflation proves more stubborn than expected. The ultimate decision will depend on incoming economic data and the evolving inflation outlook.
Investors and businesses are closely monitoring the Fed’s communication for any further clues or shifts in strategy. The clarity provided by the “next 6 months” timeframe allows for better planning and risk management, though uncertainty about the exact timing and size of each hike remains.
The upcoming Federal Reserve Rate Hikes will be a defining feature of the economic landscape in the near term.
Impact on Consumers: Borrowing Costs and Savings
For the average American consumer, Federal Reserve Rate Hikes directly translate into higher borrowing costs. Mortgage rates, credit card APRs, and auto loan rates are all expected to climb in response to the Fed’s actions.
This means that purchasing a home, financing a car, or carrying a balance on credit cards will become more expensive, potentially dampening consumer spending.
Conversely, savers may see some benefits as interest rates on savings accounts, certificates of deposit (CDs), and money market accounts increase. While these increases often lag behind borrowing rate hikes, they offer a glimmer of positive news for those with cash reserves.
However, the gains for savers might still be outpaced by the rate of inflation, meaning real returns could remain negative.
The cumulative effect of these changes will likely encourage more cautious spending and potentially higher savings rates among consumers.
Households with variable-rate debt will feel the pinch most acutely, as their monthly payments will rise. Understanding these direct impacts is crucial for personal financial planning in light of the impending Federal Reserve Rate Hikes.
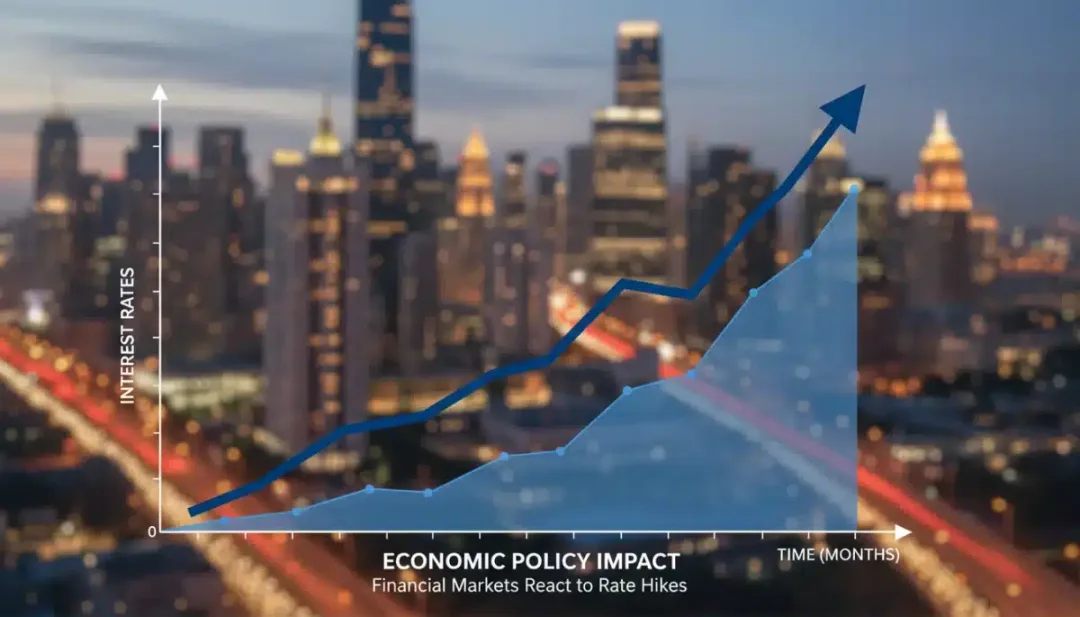
Effects on Businesses and Investment Strategies
Businesses, particularly those reliant on debt financing for expansion or operations, will also face increased costs due to Federal Reserve Rate Hikes.
Smaller businesses, which often have less access to diverse funding sources, may find it more challenging to secure affordable loans, potentially slowing down investment and job creation. Larger corporations might also re-evaluate their capital expenditure plans in light of higher borrowing expenses.
The investment landscape is also set for significant adjustments. Higher interest rates typically make bonds more attractive relative to stocks, as fixed-income securities offer better returns.
This could lead to a reallocation of capital from equity markets to bond markets, potentially causing volatility in stock prices. Growth stocks, which often rely on future earnings potential, can be particularly vulnerable in a rising rate environment.
Companies with strong balance sheets and less reliance on debt may be better positioned to weather the storm, while highly leveraged firms could face headwinds.
Investors will need to reassess their portfolios, focusing on companies with solid fundamentals and resilience to higher financing costs. The strategic implications of the Federal Reserve Rate Hikes for businesses and investors are profound.
Global Economic Repercussions and the Dollar’s Strength
The Federal Reserve Rate Hikes will not only impact the U.S. economy but also have significant global repercussions. As U.S. interest rates rise, the dollar tends to strengthen, making American goods more expensive for foreign buyers and imports cheaper for U.S. consumers.
This can affect global trade balances and potentially put pressure on countries with dollar-denominated debt.
Emerging markets, in particular, often face challenges when the Fed tightens monetary policy. A stronger dollar can lead to capital outflows from these economies as investors seek higher returns in dollar assets.
This can destabilize their financial markets and make it more expensive for them to service their dollar-denominated debt, potentially triggering economic distress in vulnerable nations.
Central banks around the world will be closely watching the Fed’s actions and may feel compelled to adjust their own monetary policies in response to maintain economic stability.
The interconnectedness of the global financial system means that the Federal Reserve Rate Hikes will send ripples far beyond U.S. borders, influencing international capital flows and exchange rates.
The Balancing Act: Inflation vs. Economic Growth
The Federal Reserve’s primary challenge is to strike a delicate balance between curbing inflation and sustaining economic growth.
Aggressive Federal Reserve Rate Hikes risk slowing down the economy too much, potentially leading to a recession and increased unemployment.
Conversely, insufficient action could allow inflation to become deeply ingrained, eroding purchasing power and long-term economic stability.
This balancing act requires careful monitoring of a wide range of economic indicators, including employment data, consumer spending, manufacturing output, and global economic trends.
The Fed’s decisions are data-dependent, meaning future policy moves will be guided by the evolving economic landscape. The goal is a “soft landing,” where inflation is brought under control without triggering a severe economic contraction.
However, achieving a soft landing is notoriously difficult, and many economists remain skeptical of the Fed’s ability to navigate this challenge flawlessly.
The path ahead is fraught with uncertainty, and the ultimate success of the Federal Reserve Rate Hikes in achieving their objectives will depend on a multitude of factors, both domestic and international.
Preparing for the Anticipated Economic Shifts
Given the strong hints of Federal Reserve Rate Hikes, individuals and businesses should begin preparing for the anticipated economic shifts.
For consumers, this might involve reviewing personal budgets, paying down high-interest debt, and exploring refinancing options for existing loans before rates climb further. Building an emergency fund also becomes even more critical in an uncertain economic environment.
Businesses should evaluate their debt structures, consider hedging strategies against rising interest rates, and optimize operational efficiencies to absorb potential increases in financing costs.
Diversifying revenue streams and maintaining healthy cash reserves can also provide a buffer against economic headwinds. Proactive planning can mitigate some of the adverse effects of tighter monetary policy.
Investors should consult with financial advisors to review their portfolios and adjust their strategies to align with a rising interest rate environment.
This could involve rebalancing asset allocations, focusing on value stocks, or exploring investments that tend to perform well during periods of inflation. Being prepared for the Federal Reserve Rate Hikes is essential for financial resilience.
| Key Point | Brief Description |
|---|---|
| Fed’s Intentions | Hints at two interest rate hikes within the next 6 months. |
| Primary Goal | To combat persistent inflation and achieve price stability. |
| Consumer Impact | Higher borrowing costs for mortgages, credit cards, and loans. |
| Business Impact | Increased cost of debt financing and potential investment slowdown. |
Frequently Asked Questions About Federal Reserve Rate Hikes
Why is the Federal Reserve considering these rate hikes?▼The Federal Reserve is considering these rate hikes primarily to combat persistent inflationary pressures. By increasing the cost of borrowing, the Fed aims to reduce overall demand in the economy, which should, in turn, help to bring down prices and stabilize the purchasing power of the U.S. dollar, aligning with its mandate for price stability.
How will these rate hikes affect my mortgage?▼If you have a variable-rate mortgage, your monthly payments are likely to increase as the Fed raises interest rates. For those planning to buy a home, new mortgage rates will be higher, making homeownership more expensive. Fixed-rate mortgages, however, will remain unaffected by these specific changes once locked in.
What does this mean for my savings accounts?▼Higher interest rates typically lead to increased returns on savings accounts, certificates of deposit (CDs), and money market accounts. While these increases may not be immediate or perfectly match the Fed’s hikes, savers can generally expect to earn more on their deposits over time, although inflation might still erode real returns.
Will these hikes cause a recession?▼The Federal Reserve aims for a “soft landing,” meaning it hopes to cool inflation without triggering a recession. However, overtightening monetary policy can indeed slow economic growth significantly, potentially leading to a recession. The Fed is walking a tightrope, balancing inflation control with the risk of an economic downturn, making the outcome uncertain.
How quickly will the effects of the hikes be felt?▼The effects of interest rate hikes are typically felt gradually across the economy. Changes in borrowing costs for new loans can be almost immediate, while impacts on inflation and broader economic activity may take several months to fully materialize. Consumers and businesses should prepare for a phased adjustment to the new financial environment as the Federal Reserve Rate Hikes take effect.
What Happens Now
The Federal Reserve’s clear signal regarding two Federal Reserve Rate Hikes in the next six months marks a pivotal moment in the nation’s economic trajectory.
This proactive stance against inflation will undoubtedly reshape financial markets, consumer behavior, and business strategies. It is crucial for all stakeholders to remain vigilant, closely monitoring upcoming economic data and official pronouncements from the Fed.
The success of these Federal Reserve Rate Hikes hinges on their ability to temper inflation without derailing economic growth, a challenging task that will require careful navigation.
We recommend staying informed through reliable news sources and consulting financial experts to adapt personal and business financial plans effectively. The coming months will be critical in determining the long-term impact of these significant monetary policy adjustments.